Lost on Paper
On the twenty-sixth of October, Anthropic filed to go public. Anthropic makes Claude. A disclosure: Token Runner is built with Claude. So we read the filing ourselves.
The filing
Anthropic took in $16.3 billion in the first six months of 2026 and booked an $80.7 billion loss. Most of that loss is the cost of becoming worth more: $72.4 billion of it is the rising value of the company's own convertible notes.
On 26 October 2026 Anthropic filed to go public, applying to list its Class A shares on the Nasdaq Global Select Market under the symbol ANT. Anthropic makes Claude. A disclosure: Token Runner is built with Claude. So we read the filing ourselves, and every figure here is the filing's own.
The money coming in
Revenue was $41 million in 2023, $386 million in 2024 and $4.6 billion in 2025. In the first six months of 2026 it was $16.3 billion. Of that, $11.6 billion came in a single quarter, April to June.
Source: Anthropic, PBC, Form S-1, as filed with the SEC on October 26, 2026 (EDGAR, CIK 2130357)
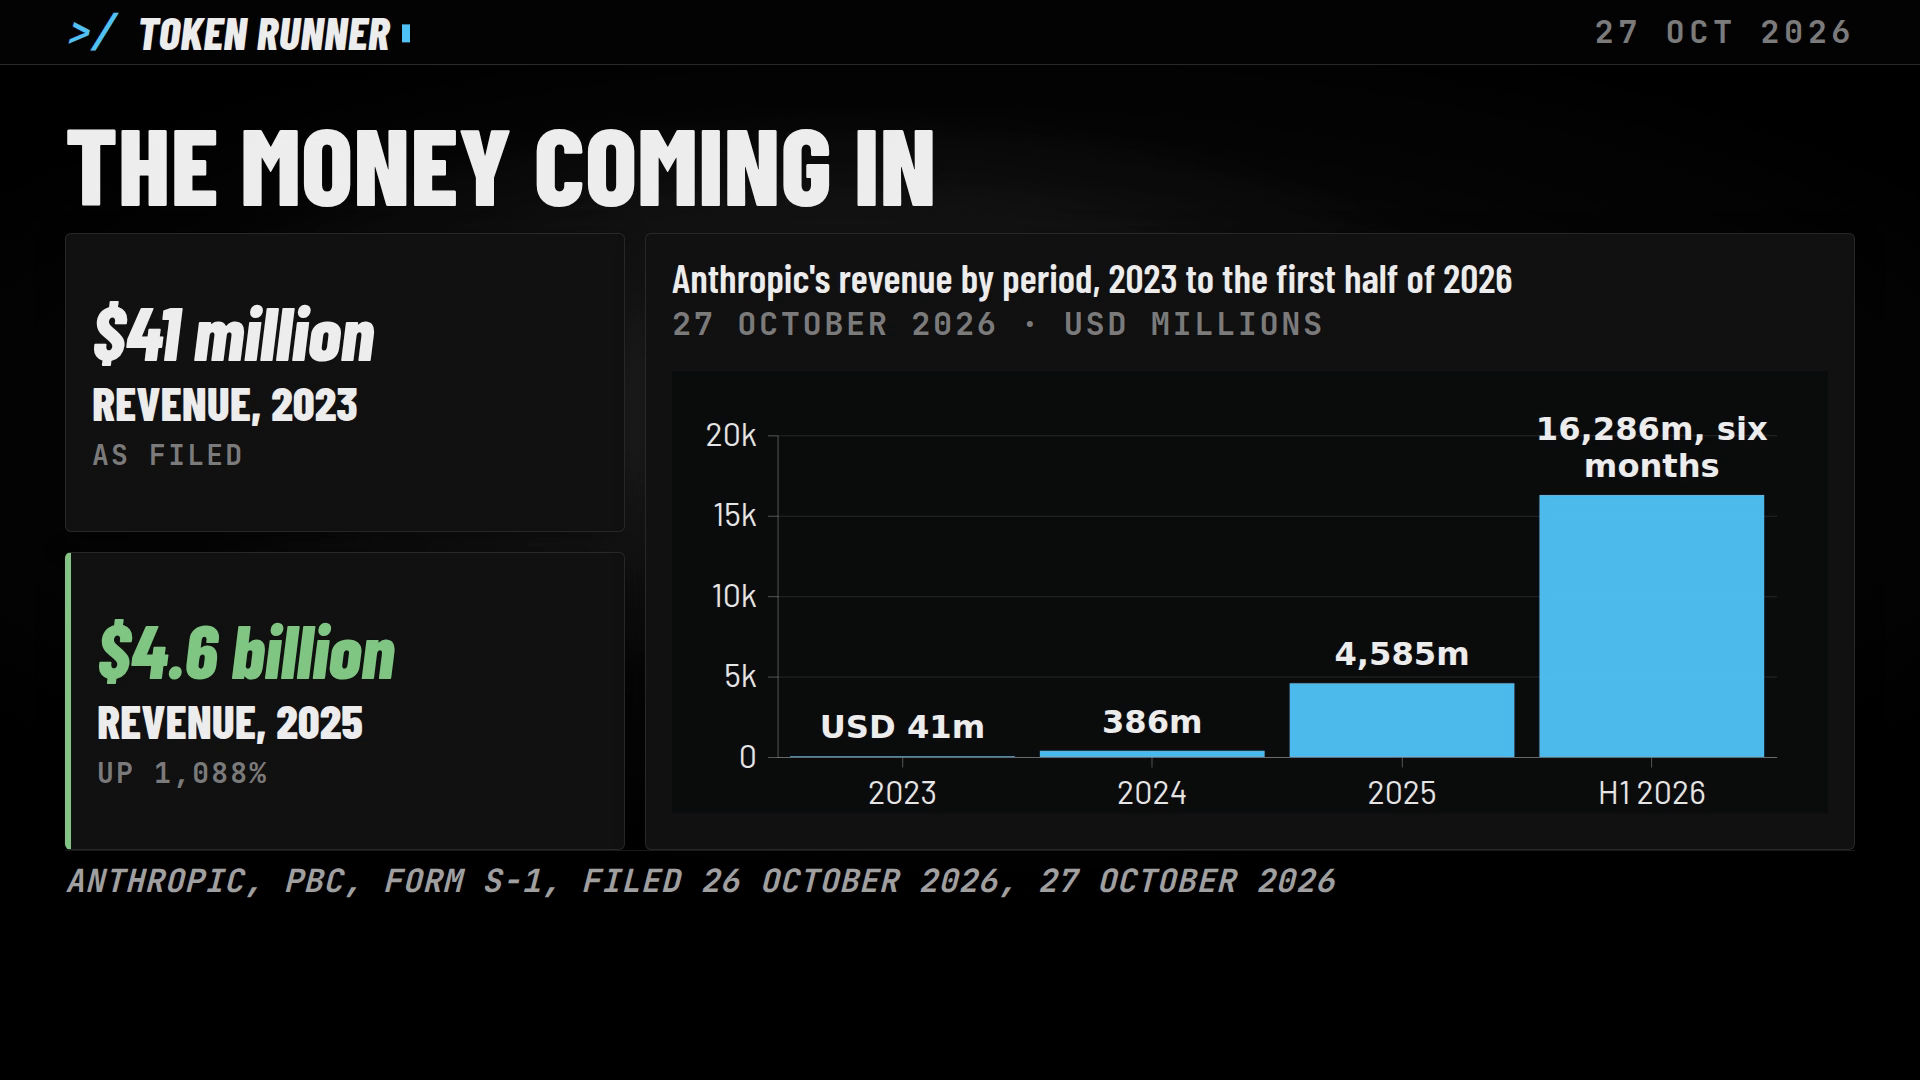
The filing's own words: "In 2023, 2024, and 2025, our revenue was $41 million, $386 million, and $4.6 billion, respectively, representing year-over-year growth rates of 841% and 1,088%, respectively." The half to 30 June 2026 brought $16,286 million against $1,163 million a year earlier.
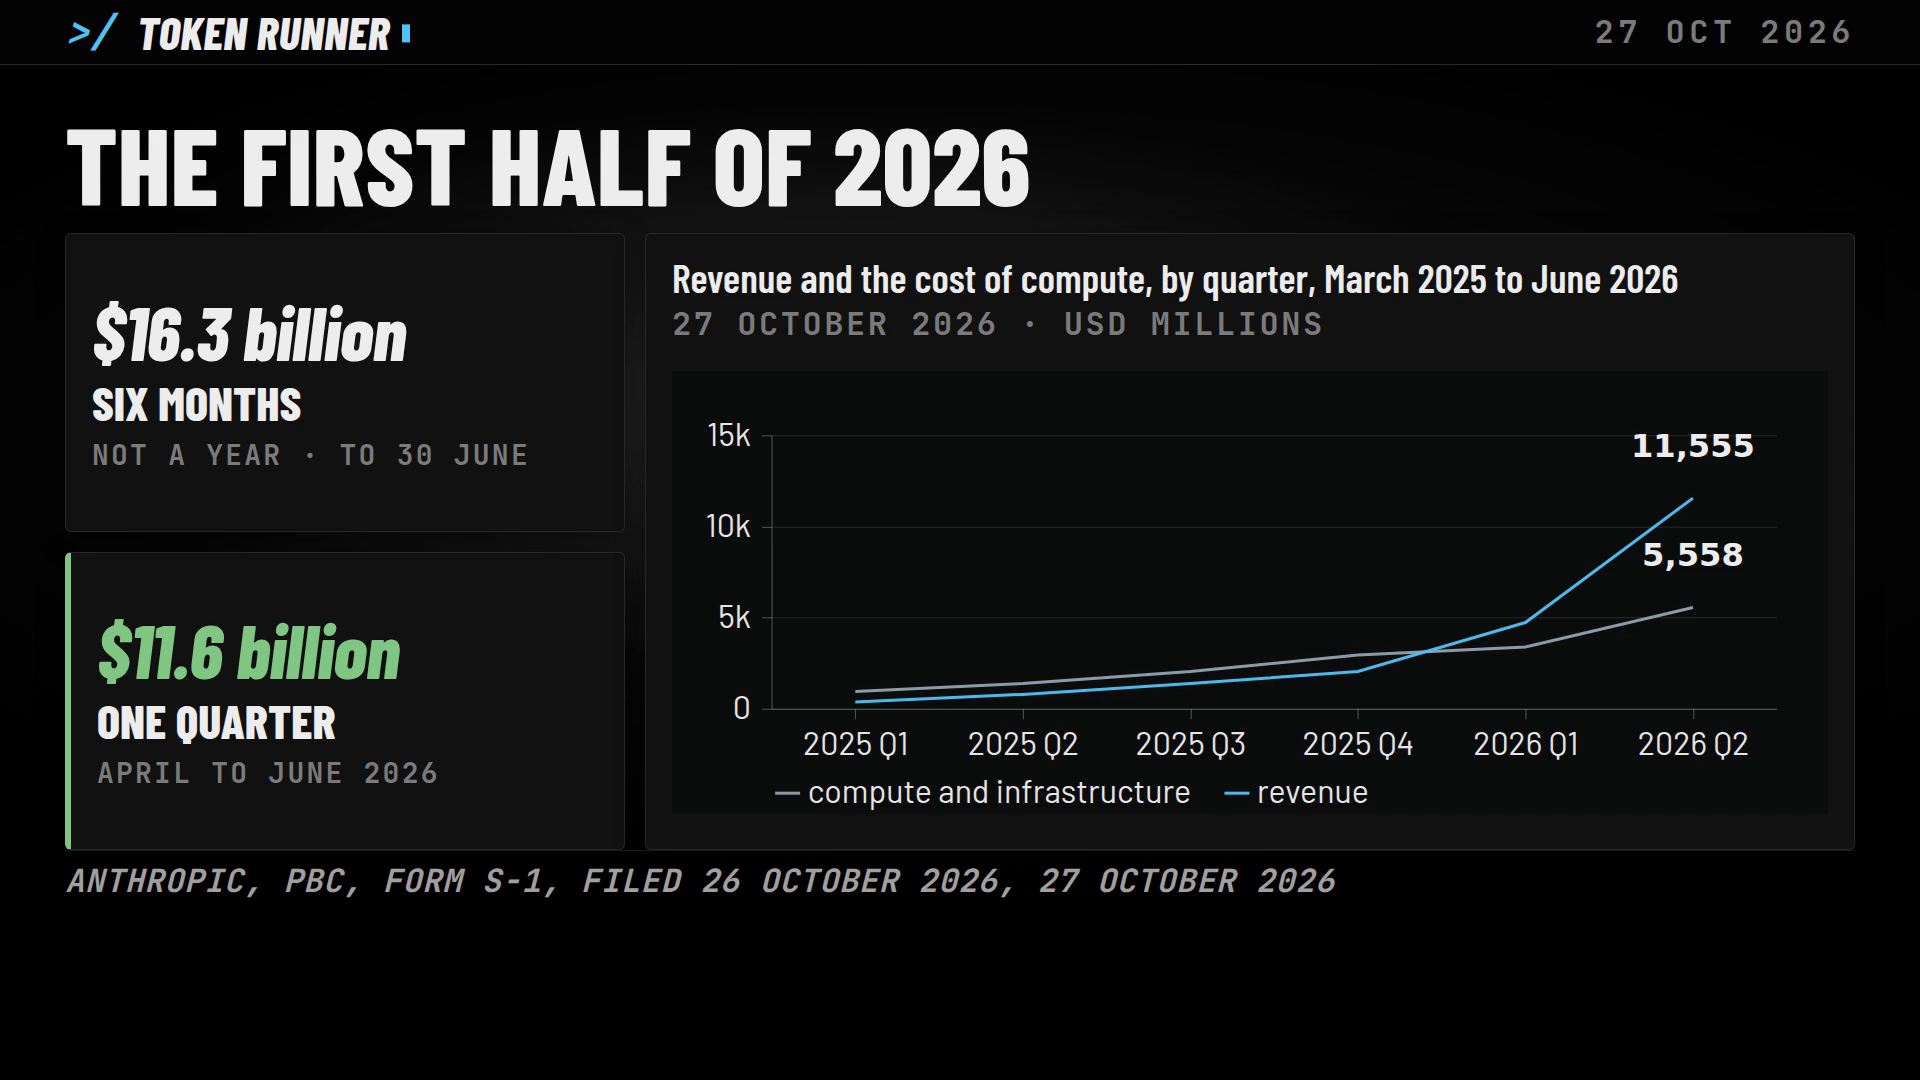
The quarterly table: $376 million, $787 million, $1,382 million, $2,040 million, $4,731 million and $11,555 million for the six quarters from March 2025 to June 2026. Compute and infrastructure grew too, but more slowly, and in the second quarter of 2026 revenue passed it.
Source: Anthropic, PBC, Form S-1, as filed with the SEC on October 26, 2026 (EDGAR, CIK 2130357)
The loss
Then the other number: a net loss of $80.7 billion for the same six months. That sounds like a company on fire. It isn't, quite.
Source: Anthropic, PBC, Form S-1, as filed with the SEC on October 26, 2026 (EDGAR, CIK 2130357)
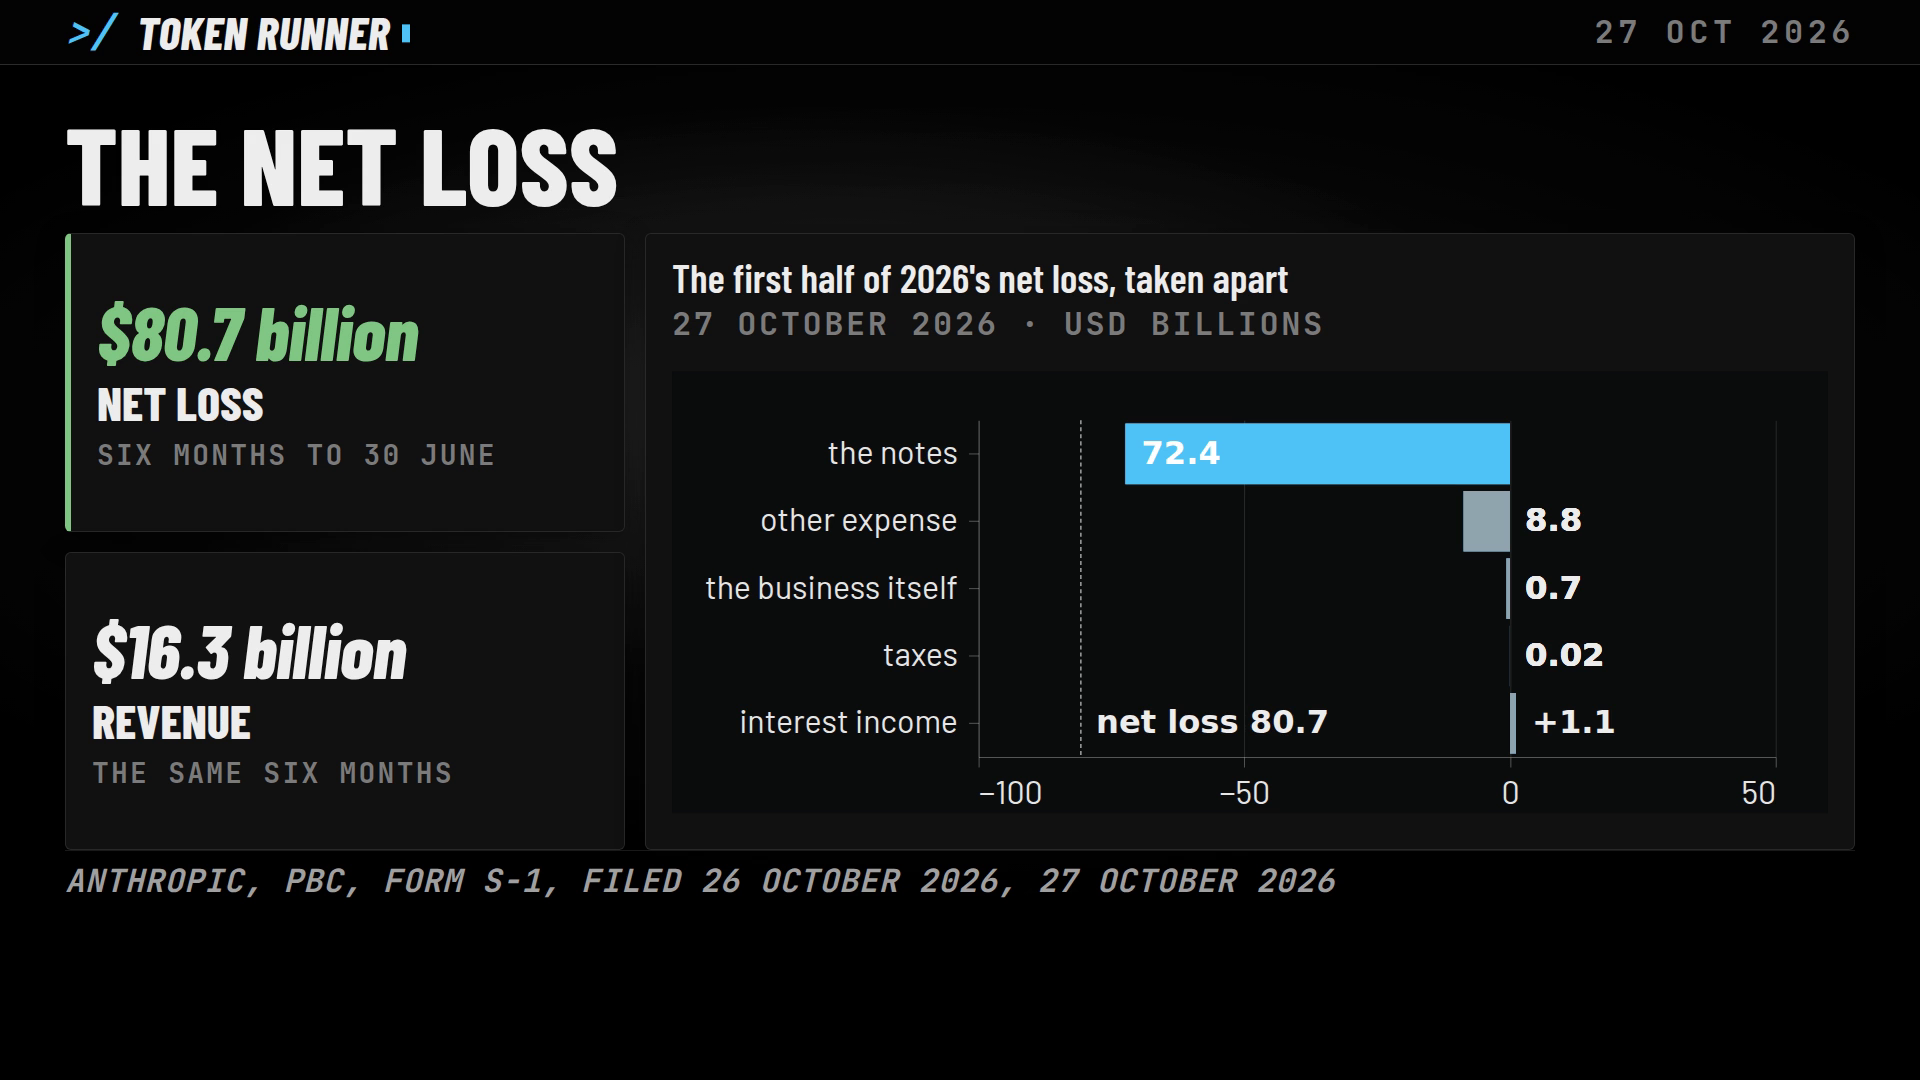
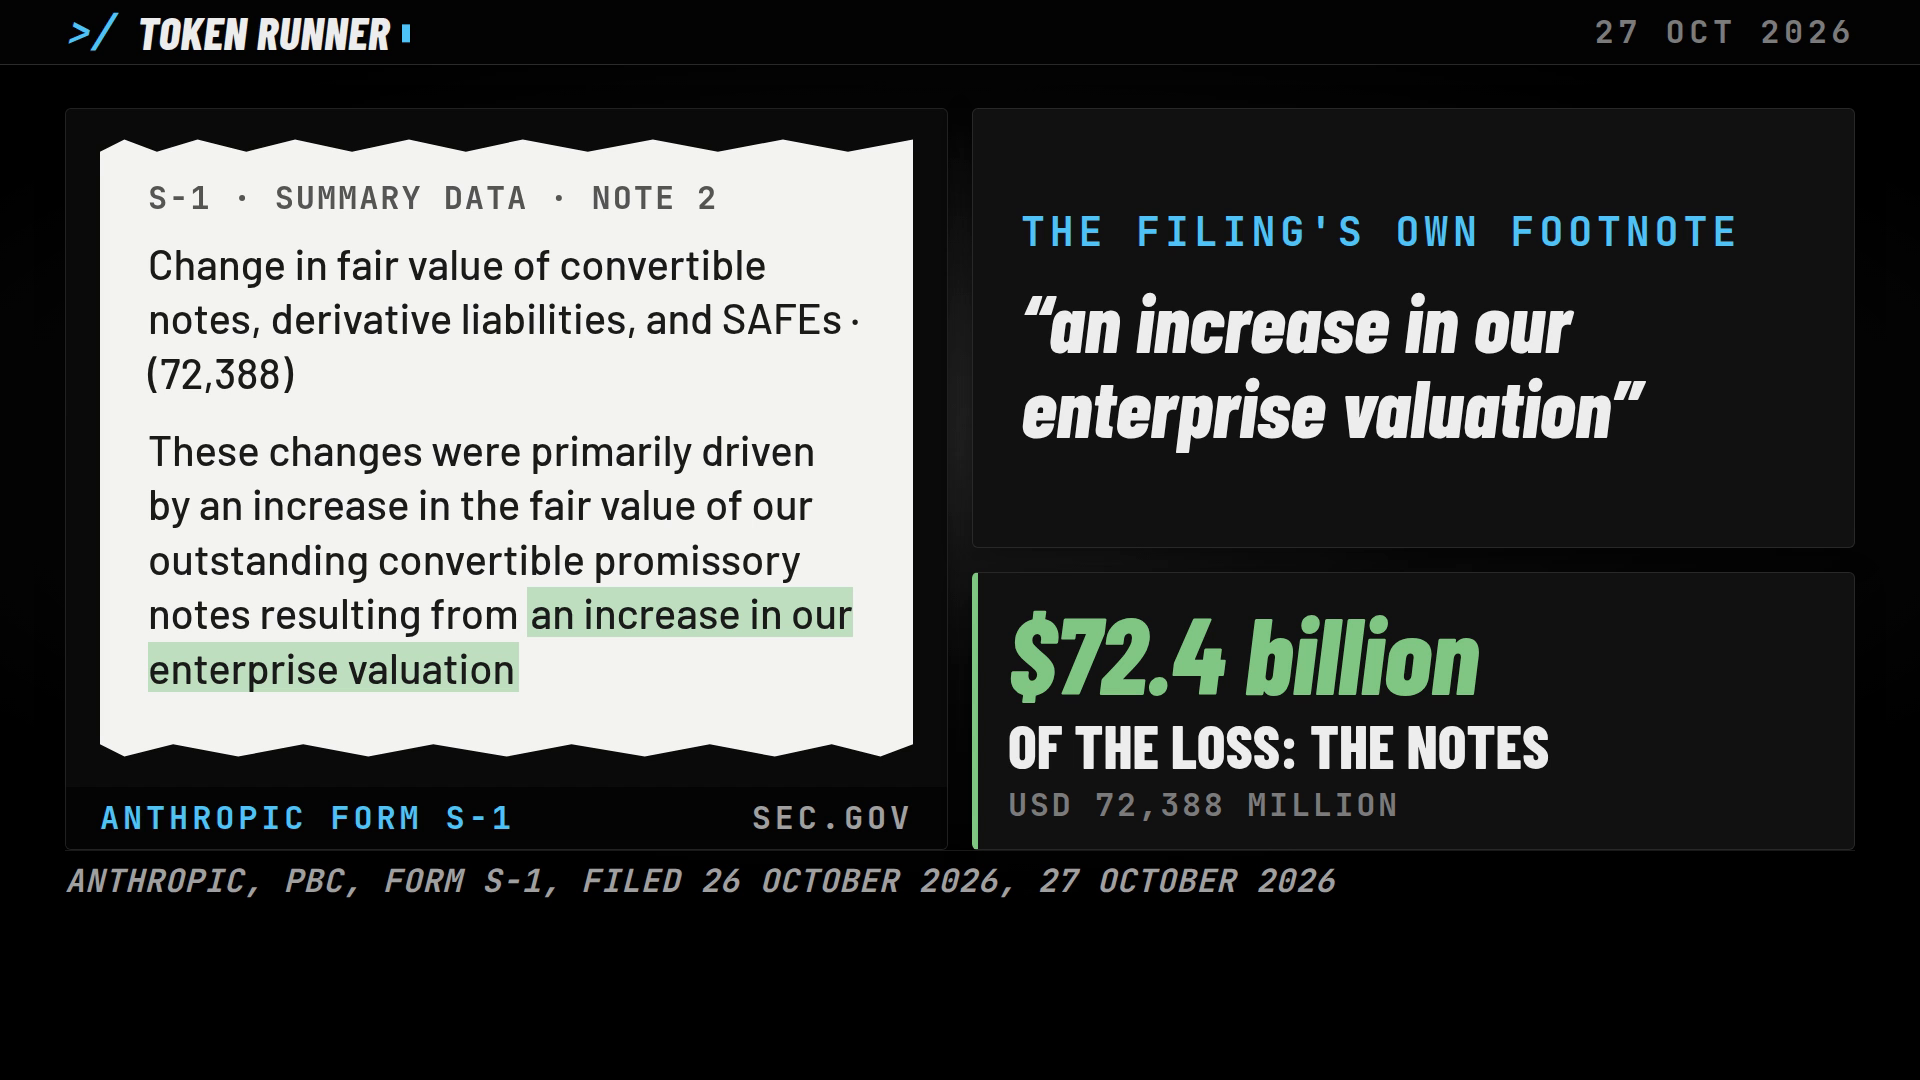
The net loss for the half is $80,748 million. It is an operating loss of $693 million; a change in the fair value of convertible notes, derivative liabilities and SAFEs of $72,388 million; other expense of $8,757 million; interest income of $1,111 million; and taxes of $21 million. The other expense, the filing says, "was primarily driven by the initial fair value recognition and change in fair value of the assets and liabilities recognized under the note purchase agreements described in Note 4".
The notes
$72.4 billion of the loss is the company's own debt: notes that turn into shares. As Anthropic became worth more, those notes became worth more, and the accounts count that as a loss.
The notes are Amazon's. Amazon holds $6.2 billion of convertible promissory notes, the company's whole indebtedness at 30 June 2026, and no note converts if Amazon "would hold more than 12% of our capitalization".
The business itself
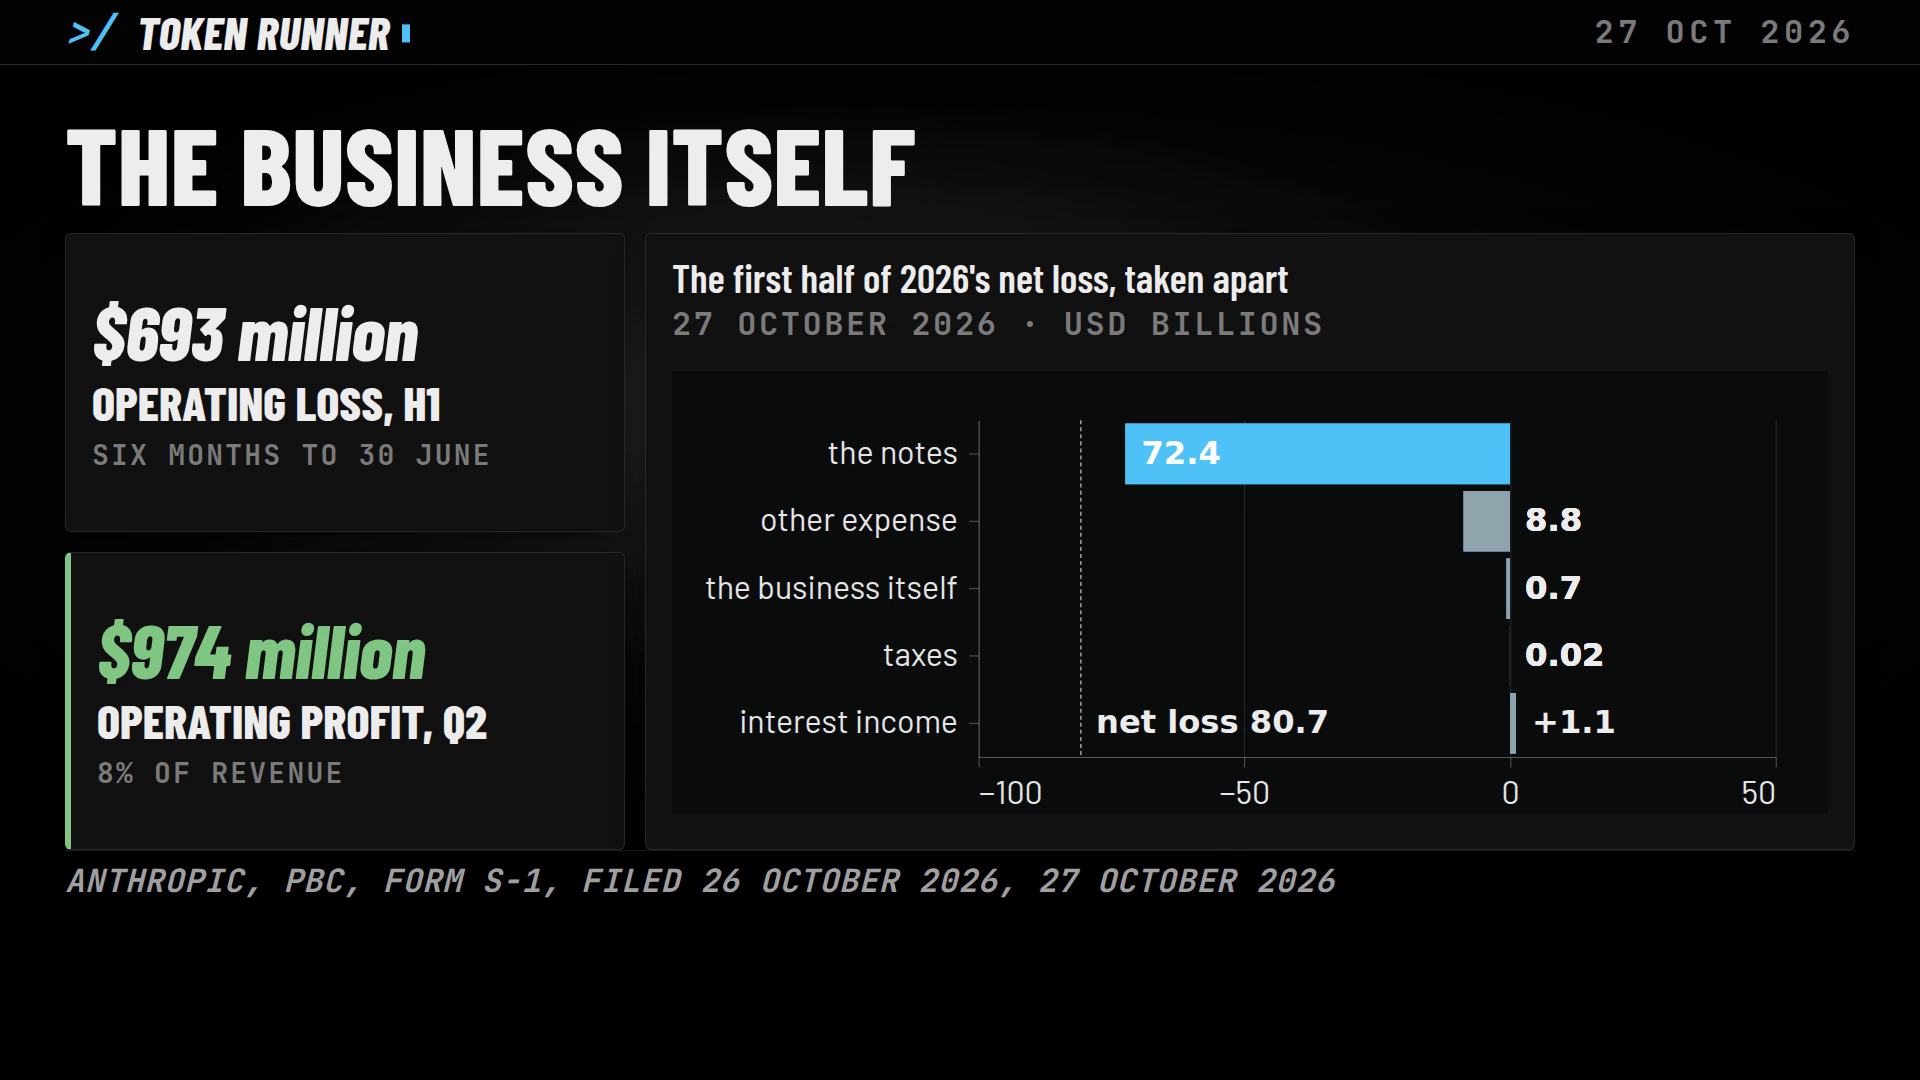
The business itself lost $693 million in the half. And in the second quarter it made an operating profit of $974 million, 8% of revenue.
That profit came after operating losses of $935 million, $1,200 million, $3,089 million, $2,836 million and $1,667 million in the five quarters before. The text rounds the quarter to "$1.0 billion". The filing's non-GAAP measure, adjusted operating income, was $1,618 million for the half.
Where the money goes
Fifty-five cents of every revenue dollar went to compute: the chips and the data centres. In the second quarter it was 48 cents.
Source: Anthropic, PBC, Form S-1, as filed with the SEC on October 26, 2026 (EDGAR, CIK 2130357)
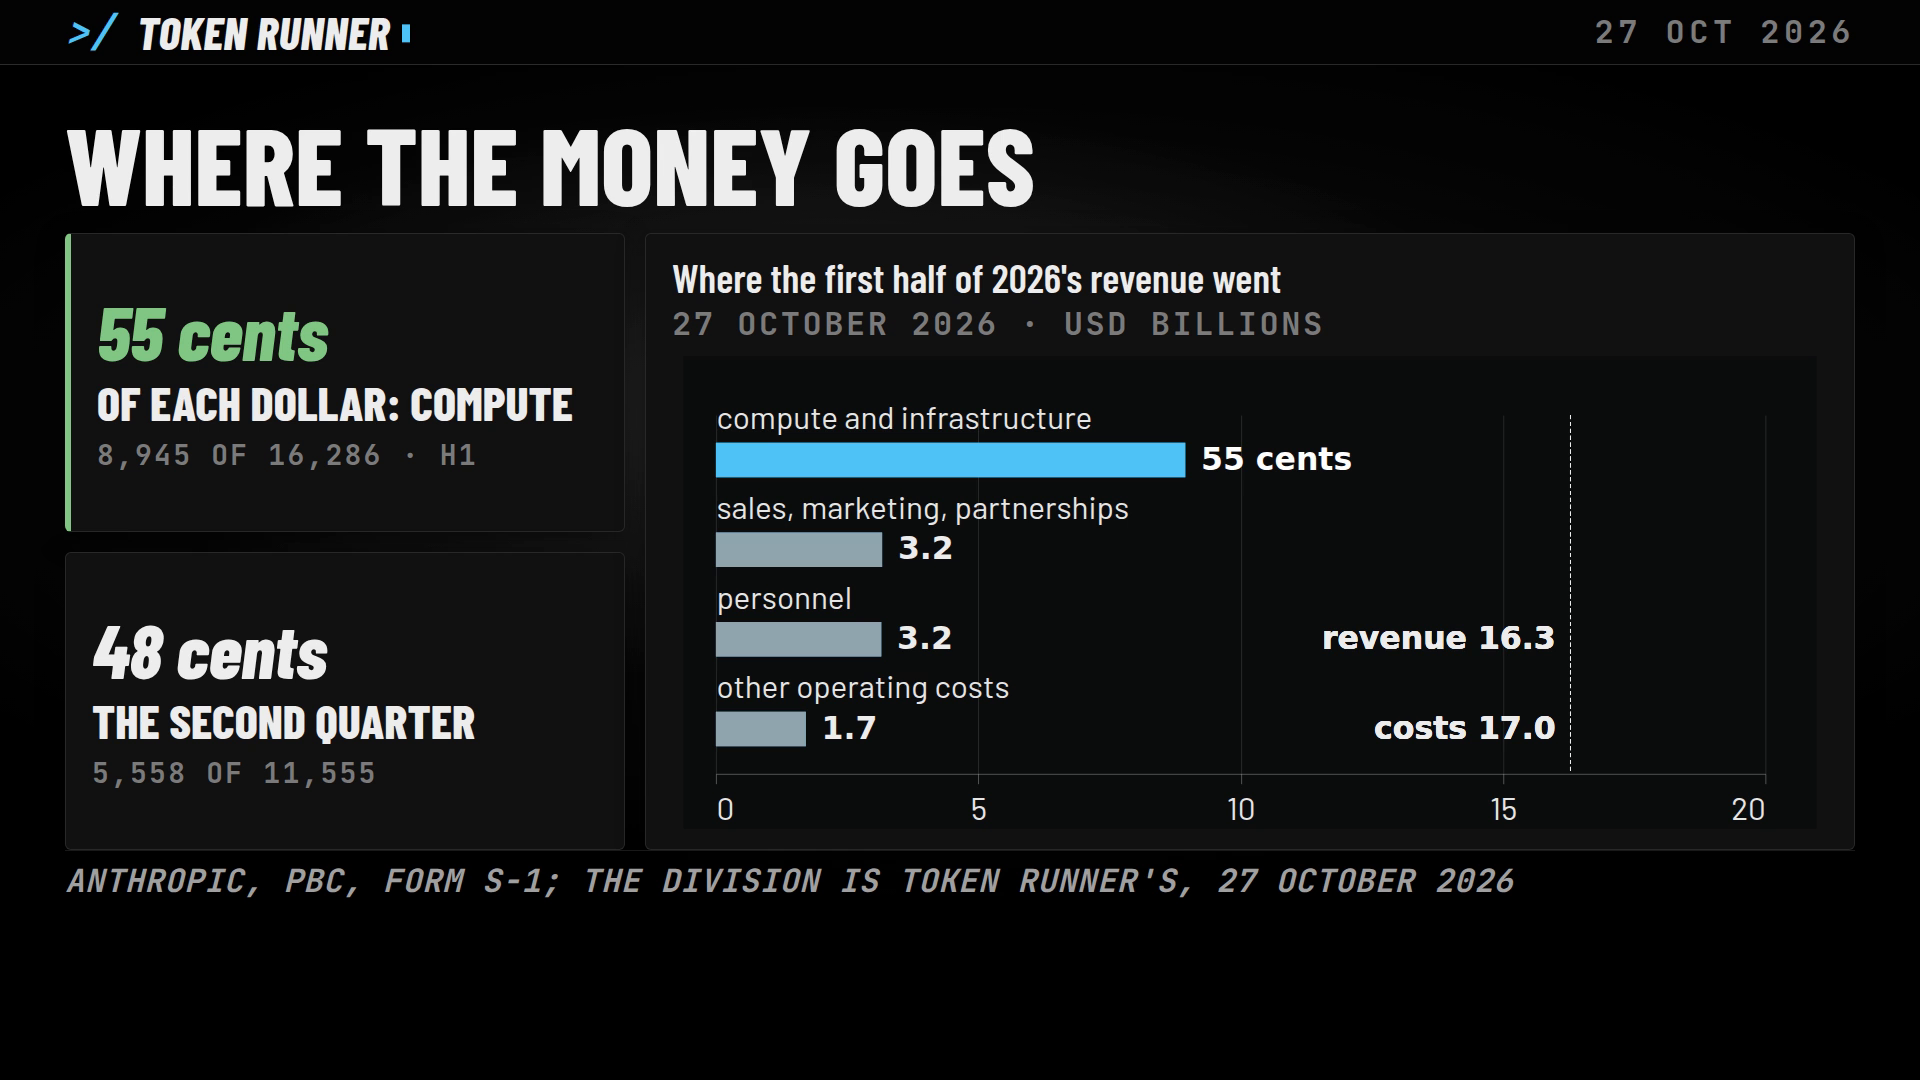
Operating expenses were $16,979 million against revenue of $16,286 million in the half. Compute and infrastructure took $8,945 million, about 55 cents of each revenue dollar by our division; in the second quarter $5,558 million of $11,555 million. Sales, marketing and partnerships took $3,168 million; personnel $3,152 million, including $2.2 billion of stock-based compensation; other operating and administrative $1,714 million. In the quarter to March 2025, compute had cost 251% of revenue.
Before 2026, the filing says, the company "obtained substantially all of its compute infrastructure from three cloud service providers". In March 2026 it signed an equipment lease with Broadcom for AI accelerators, payable if needed with up to $42.0 billion of convertible notes at 9.00% a year, paid in kind, or 13.00% if revenue conditions are missed. None had been issued at 30 June 2026.
Who holds the keys
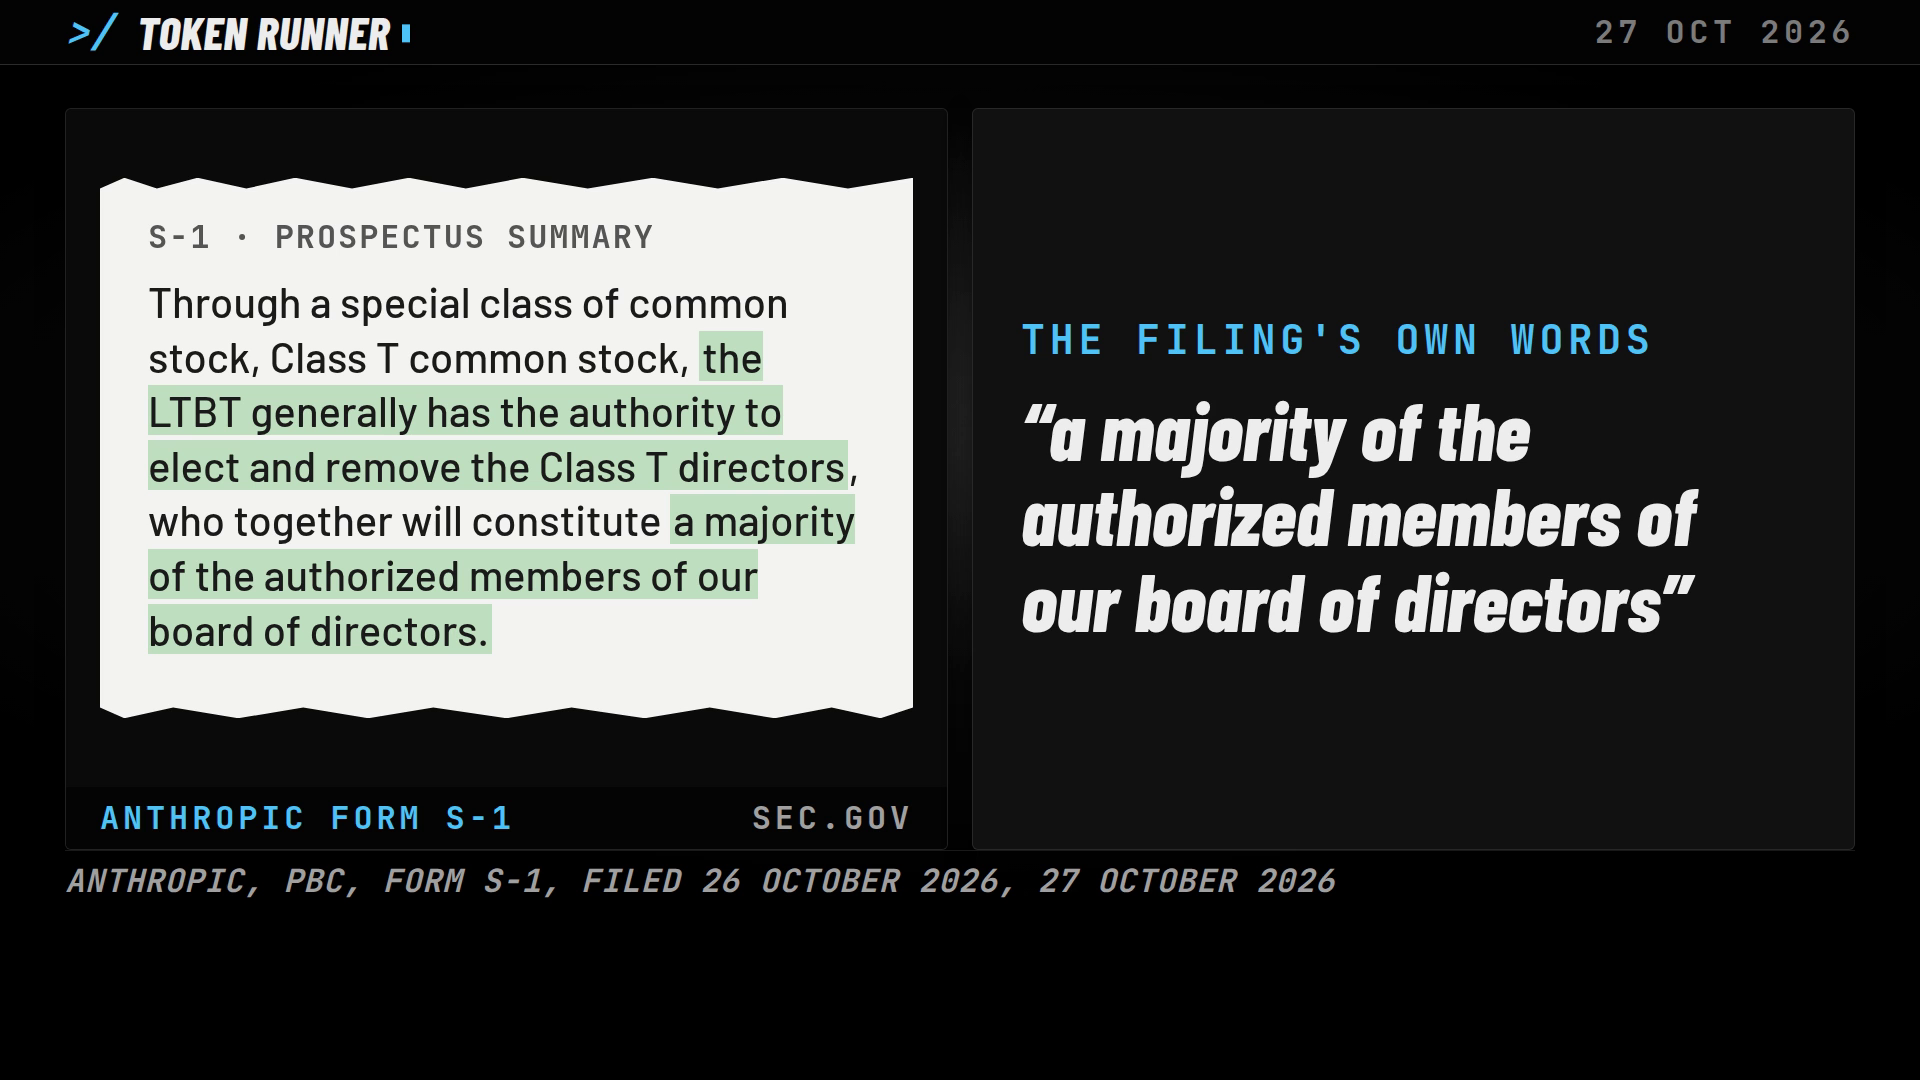
Not only the buyers of the shares. A trust of independent trustees picks most of the board, through a special class of stock the trust holds.
The Class T stock "does not otherwise have voting rights with respect to matters submitted to stockholders generally and has no economic rights". The trust is "an independent body of five financially disinterested Trustees", and the company is "incorporated as a public benefit corporation under Delaware law". The shares offered to the public are Class A.
The customers
As of 30 September 2026, the filing counts more than 11,900 customers paying $100,000 or more a year, more than 1,900 paying $1 million or more, and about 250 paying $10 million or more. It had about 5,300 employees.
At 30 June 2026 it held cash, cash equivalents and short-term investments of $131,651 million, total assets of $147,358 million and total liabilities of $117,467 million, with an accumulated deficit of $132,902 million. 2025's costs include a $1,500 million settlement, the Bartz settlement. About 47% of 2025's revenue and 48% of the first half of 2026's came through the cloud providers' marketplaces. One customer was 43% of 2023's revenue.
Source: Anthropic, PBC, Form S-1, as filed with the SEC on October 26, 2026 (EDGAR, CIK 2130357)
On power, the filing says data-centre development in some of the regions where it has contracted compute "has prompted public controversy and regulatory scrutiny regarding environmental impact, land and water use, and the allocation of limited power resources."
To be fair
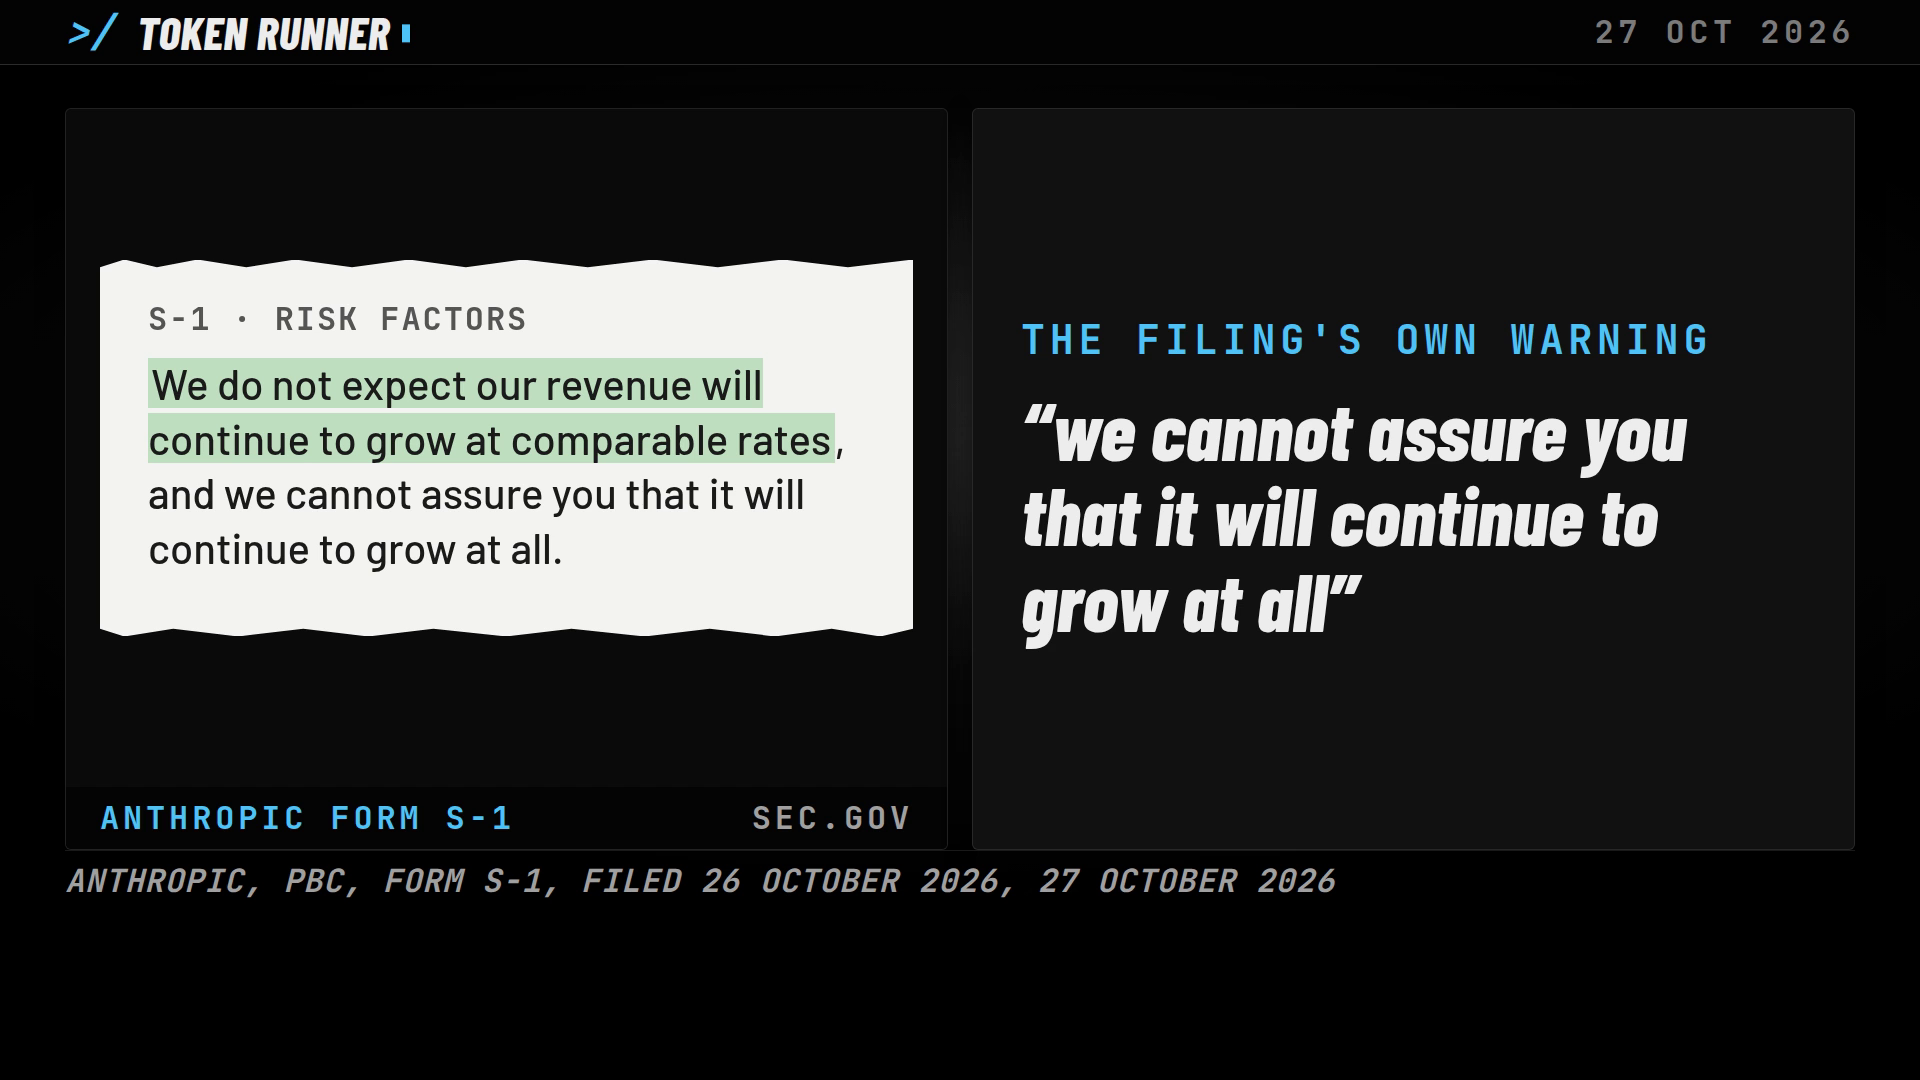
The filing warns about itself: it does not expect revenue to keep growing at these rates.
And it leaves things blank, as filed: the price range and the share count; the contractual obligations table, whose total "approximately $" and every cell are empty, "substantially all of which is related to compute and infrastructure"; and its estimate of other compute payments, "approximately $ to $". The reported timing and valuation of the offering are press reports, not the filing's.
A price on paper
Sixteen billion dollars in, in six months.
A loss that is mostly paper: $72.4 billion of $80.7 billion is the notes.
And a market about to put a price on it, in a filing whose price range is still blank.
Every figure from Anthropic's own filing. Anthropic makes Claude, and Token Runner's agents run on Claude.